Retro Pay Calculator 2026: Calculate Retroactive Pay & Overtime
2026 payroll guide · United States · Free workweek audit
A delayed raise can affect more than one paycheck—and more than the standard hours on your timecard. Use this retro pay calculator for 2026 to compare old and corrected wages, calculate overtime rate adjustments, subtract corrections already paid, and produce a week-by-week audit.
Retro pay is additional compensation owed when wages should have been calculated at a different rate in a previous period. For a simple hourly correction, multiply the rate difference by the affected straight-time hours and by the applicable overtime multiplier for overtime hours. Subtract any retro adjustment that has already been paid. Your actual withholding and final take-home amount depend on payroll circumstances.
2026 Retro Pay & Paycheck Audit Calculator
Three calculation modes. For hourly work with changing schedules, choose the workweek audit. Values stay in this page's calculator; no account is needed.
Your itemized retro pay audit
| Period / week | Old gross | Correct gross | Rate difference | Paid credit | Still owed |
|---|---|---|---|---|---|
| Totals | — | — | — | — | — |
Optional withholding estimate on unpaid retro wages
| Withholding assumption | Amount |
|---|---|
| Assumed federal income tax | |
| Assumed state/local withholding | |
| Employee Social Security (6.2%, wage base applied) | |
| Regular employee Medicare (1.45%) | |
| Additional Medicare withheld (0.9% above employer threshold) | |
| Estimated net retro pay |
Educational estimate. Verify workweek records and payroll policy before using this as a wage claim or payroll instruction.
What is retro pay?
Retro pay (retroactive pay) is an adjustment for compensation that should have been paid in an earlier period. Examples include an approved raise entered late, a corrected job classification or pay rate, and a negotiated increase made effective on a prior date. It commonly appears on a pay stub as RETRO, RET PAY, or PAY ADJ, although labels differ by payroll system.
Start with the correct effective date, not the date the raise was announced. Then compare what was actually paid with what should have been paid, taking overtime, periods already adjusted, and eligible payroll premiums into account. If entire shifts went unpaid, you may need a broader back pay calculation instead of this rate-adjustment model.
(Correct rate − paid rate) × regular hours + (correct rate − paid rate) × overtime hours × applicable multiplier.
Subtract any retro correction already paid to find the remaining amount owed.
How to calculate retro pay accurately
- Find the earliest corrected effective date. Check the signed raise notice, contract, collective bargaining agreement, or employer correction notice.
- Obtain the original work records. Review actual workweeks, hourly rates, overtime hours, timecards, and original payroll amounts.
- Assign each workweek separately. Use the workweek audit above when rates, hours, or premium rules change. A biweekly pay period may contain two different FLSA workweeks.
- Calculate regular and overtime rate differences. In the typical 1.5× example, a $2 hourly retro increase produces $2 more per straight-time hour and $3 more per overtime hour.
- Subtract a correction already issued. Enter only prior retro correction amounts relating to the same included hours; never subtract the original paycheck twice.
- Confirm gross wages first. Estimate employee withholding only after the corrected gross pay is reconciled with payroll records.
2026 retro pay examples with verified arithmetic
Example 1: One workweek with overtime — $95 owed
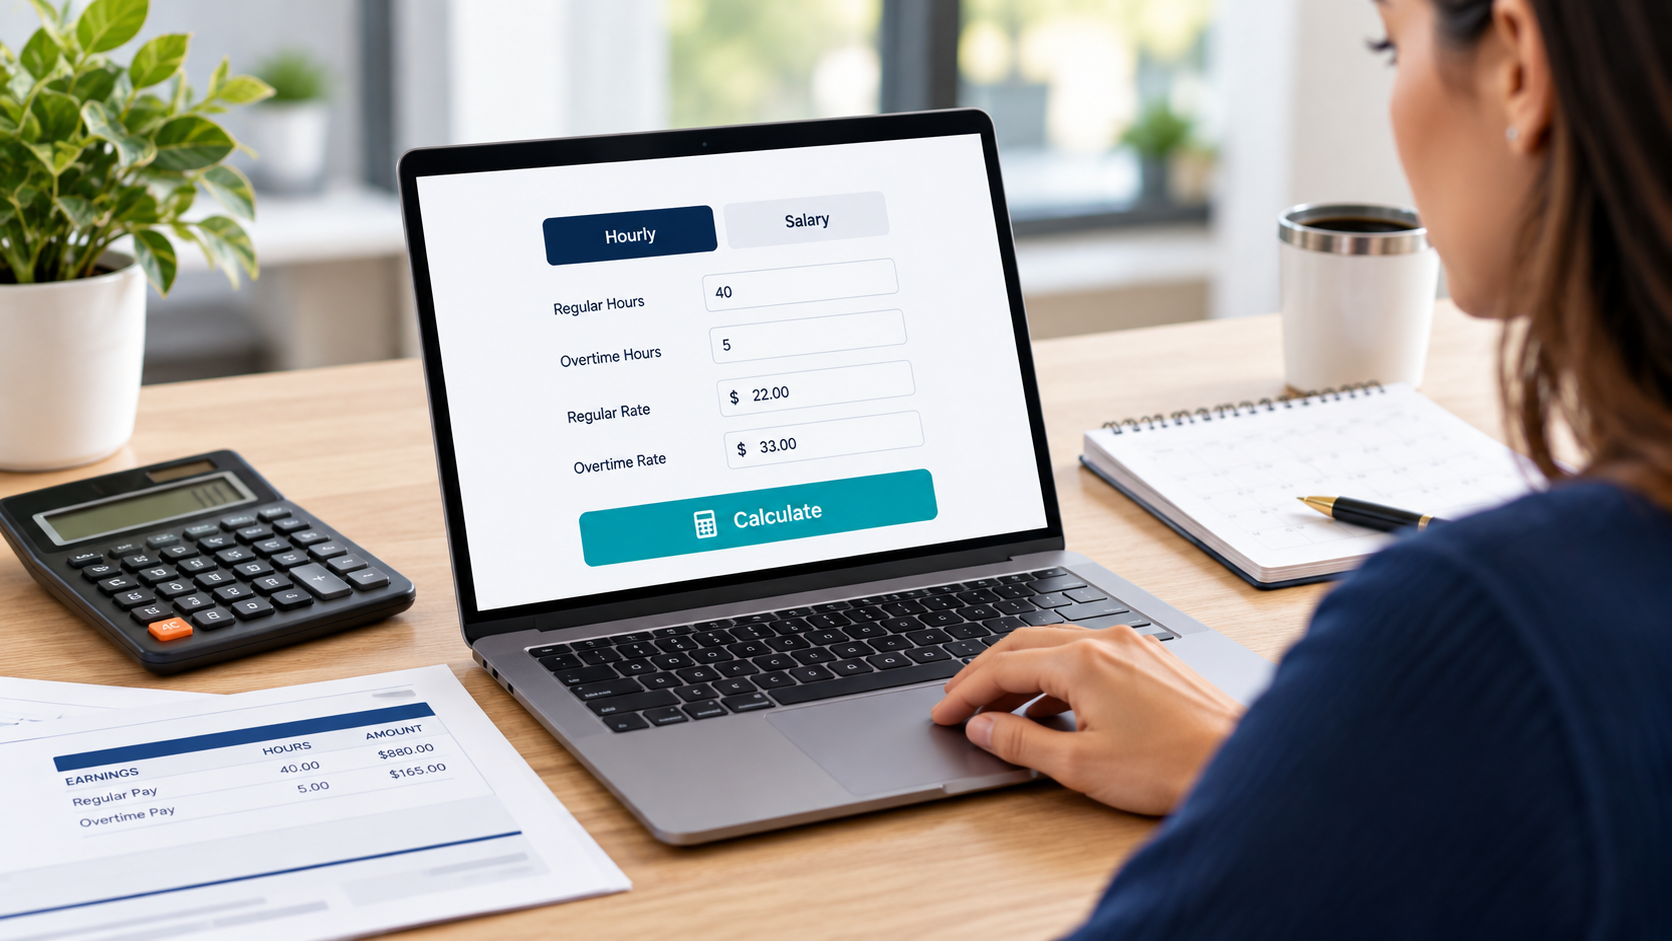
A covered nonexempt employee originally earned $20/hour. A raise to $22/hour applied to a week containing 40 regular hours and five overtime hours at 1.5×. Assume the original paycheck was calculated at the old rate and there were no other earnings affecting the regular rate.
| Earnings | Original pay | Correct pay | Difference |
|---|---|---|---|
| Regular: 40 hours | $800.00 | $880.00 | $80.00 |
| Overtime: 5 hours × 1.5 | $150.00 | $165.00 | $15.00 |
| Gross wages | $950.00 | $1,045.00 | $95.00 |
Of the $95 correction, $90 represents a $2 base-rate difference across 45 worked hours. The remaining $5 is the extra half-time overtime premium on five overtime hours. This distinction catches the common mistake of multiplying $2 by 45 and stopping at $90.
Example 2: Three workweeks, changing rates, one correction already paid
Suppose the employee has three workweeks affected by a delayed rate change. Week 2 already received a $10 retro adjustment. The calculation must credit that amount without erasing the original wages paid.
| Workweek | Old → correct rate | Hours | Gross rate correction | Already paid | Still owed |
|---|---|---|---|---|---|
| September 7 | $20 → $22 | 40 regular, 5 overtime | $95.00 | $0.00 | $95.00 |
| September 14 | $20 → $22 | 40 regular, 2 overtime | $86.00 | $10.00 | $76.00 |
| September 21 | $21 → $23 | 32 regular, 0 overtime | $64.00 | $0.00 | $64.00 |
| Totals | $245.00 | $10.00 | $235.00 | ||
Choose Load 3-week example in the calculator to reproduce this scenario. Its CSV export preserves the period-level audit rather than just the final result.
Example 3: Retroactive salary increase
An employee's annual base salary increases from $52,000 to $58,000. For 26 biweekly periods, the full-period difference is $6,000 ÷ 26 = approximately $230.77. Two full affected biweekly periods yield $461.54 using final rounding. If the employee was affected for seven eligible days of an additional 14-day period, the illustrative partial-period amount is another $115.38, for an estimated $576.92 overall.
Employers may prorate salary differently based on the dates and pay plan. This simple salary mode does not compute FLSA overtime owed to nonexempt salaried workers, nondiscretionary bonuses, or nonstandard regular-rate adjustments.
Original visual paycheck comparison: how RETRO changes gross pay
These illustrative earnings-only statements use Example 1. They are fictional, not employer-issued pay stubs, and intentionally omit personal data, deductions, net wages, and legal document formatting.
Illustrative earnings comparison created for this article. The difference is $95 gross. It does not mean payroll should replace or falsify the original issued statement.
The overtime rule that changes retro pay
Under 29 CFR § 778.303, a retroactive pay increase can raise the regular rate for covered prior workweeks. In the regulation's simple example, a 10-cent increase in the base rate adds 15 cents for each affected overtime hour when overtime is paid at time-and-a-half.
Why this matters: the proper comparison includes the corrected overtime premium, not merely the change in straight-time hourly wages. Our workweek calculator separately shows the extra overtime premium to make that part of the audit easier to identify.
Scope limit: This tool assumes one base hourly rate per row, overtime hours and applicable multiplier already known, and the old overtime pay having been calculated at the old base rate with the same multiplier. It does not automatically decide overtime eligibility, blend multiple concurrent job rates, allocate retroactive lump-sum bonuses, calculate commissions, determine shift differentials, model federal 7(k) work periods, or handle all state wage laws. Those scenarios may require individual payroll computations under 29 CFR Part 778. Use the DOL overtime fact sheet for federal basics.
Is retro pay taxed differently in 2026?
Retro pay is generally taxable compensation, but a separate 22% federal withholding rate does not apply automatically. IRS Publication 15 (2026), Section 7 specifically lists retroactive pay increases among supplemental wages. How an employer withholds federal income tax depends on whether the payment is separately identified and which supplemental-wage method and requirements apply. A qualifying employer may use the optional flat 22% method on eligible supplemental wages, while combined-pay or aggregate-method calculations may yield another withholding result. Payments exceeding $1 million in annual supplemental wages have special rules.
Income-tax withholding is not the same as the employee's final income-tax liability for the year. Retro pay can also be subject to Social Security and Medicare taxes. The optional calculator above applies simplified employee FICA calculations to the unpaid incremental amount, using the YTD wage bases entered. It does not calculate filing-status-dependent annual tax liability or a full Form W-4 withholding schedule. For individualized paycheck withholding, consult the IRS Tax Withholding Estimator.
| 2026 employee component | Basic rule | Key condition |
|---|---|---|
| Federal income-tax withholding | Employer follows the applicable payroll/supplemental-wage method. | 22% only when eligible; not automatically a final tax rate. |
| Social Security / OASDI | 6.2% of covered employee wages | 2026 $184,500 annual wage base per employer under ordinary rules. |
| Medicare | 1.45% of covered wages | No annual covered-wage cap. |
| Additional Medicare withholding | 0.9% on wages above employer's $200,000 withholding threshold | Final individual liability depends on filing status and other facts. |
| State / local withholding | Varies | Calculator accepts user-supplied assumed percentage only. |
If 2026 covered wages before the check total $184,000 and a $1,000 retro payment is made by the same employer, only $500 remains below the Social Security wage base. The additional employee Social Security withholding would be $31.00, not $62.00, assuming the correction is otherwise covered and the YTD wages are complete. Regular Medicare withholding on the full $1,000 would generally be $14.50. See the ePaystubs 2026 FICA guide for a more detailed wage-base calculator.
Retro pay versus back pay, missed hours, and bonuses
| Situation | Usually relevant calculation | Best next step |
|---|---|---|
| Raise effective two weeks before payroll updated it | Retro rate difference plus applicable overtime true-up | Use workweek audit |
| Entire shift or workweek omitted | Unpaid hours plus applicable premiums | Reconcile timecards and payroll |
| Late nondiscretionary bonus | Allocation over relevant workweeks may change overtime regular rate | Use specialized bonus/overtime guidance |
| Retro salary increase without overtime impact | Salary difference by eligible pay periods | Use salary mode with employer proration policy |
| Union rate increase with multiple classifications | Distinct rate periods and possibly special regular-rate calculations | Reconcile contract and payroll workweeks |
Seven mistakes that produce the wrong retro amount
- Starting on the announcement date. Use the effective date supported by records.
- Applying the wrong overtime multiplier. Confirm the actual eligible overtime premium and contract/state requirements.
- Ignoring the extra half-time overtime premium. A $2 raise on five 1.5× overtime hours requires a $15 correction, not $10.
- Mixing pay periods with FLSA workweeks. One paycheck may contain workweeks with different rates or overtime totals.
- Subtracting the original paycheck twice. The gross rate difference already accounts for the original wages; only subtract retro credits already paid.
- Using an automatic 22% tax assumption. The IRS method depends on employer circumstances; final tax differs from withholding.
- Claiming every salary is overtime-exempt. Salary status alone does not establish a federal overtime exemption.
How to check a retro payment on your next paycheck
Suppose the current paycheck includes $1,250 in current regular wages and a separately labeled $95 RETRO earnings adjustment for an earlier workweek. Before any other current earnings, the combined gross is $1,345, not $1,250 plus a second replacement paycheck. The $95 is an incremental correction for an amount previously underpaid, rather than a new set of hours worked this week.
Illustrative current-check reconciliation
| Current statement earnings | Amount | What the line means |
|---|---|---|
| REG · current pay period | $1,250.00 | Current-period earnings |
| RETRO · previous rate adjustment | $95.00 | Gross wage correction for a prior workweek |
| Illustrative current gross | $1,345.00 | Before payroll taxes and deductions |
Fictional illustration only. Employer payroll codes and statement formats vary. Compare the original pay stub, approved rate, workweeks, adjustment check, and current/YTD totals rather than attempting to alter an issued statement.
A late adjustment is typically included in the payroll records and wage reporting for the year of payment under applicable payroll tax rules, but cross-year adjustments, corrections to wage statements, and special circumstances require payroll-specific handling. The calculator does not prepare amended tax forms.
Paycheck audit checklist before contacting payroll
- Save the wage notice showing original and corrected rates and exact effective date.
- Export or capture a record of workweek start dates, timecards, and paid overtime.
- Identify all pay statements covering the affected workweeks and any off-cycle corrections.
- Reconcile each week, then compare the total to any RETRO / ADJ earnings line.
- Check current versus year-to-date gross and taxes, and avoid counting the same correction twice.
- Request a written explanation of any unexplained discrepancy from payroll or HR. Do not send Social Security numbers or bank details in an unsecured message.
For reconciliation beyond changed rates, see the pay stub hours versus timecard guide, year-to-date pay stub guide, and taxable wage bases guide.
How long does retro pay take to appear on a paycheck?
There is no single universal processing timeframe that applies to all employers and situations. The payment date can depend on the payroll cutoff, the reason for the correction, your contract and applicable state wage-payment rules. Ask payroll for the effective dates, calculation, and the specific paycheck or off-cycle payment date.
Does retro pay affect year-to-date earnings and the W-2?
Retro compensation generally increases earnings reported through payroll when it is actually paid, with the tax-year and wage-base treatment determined under applicable rules. Compare your current and YTD earnings after the adjustment; for previous-year errors or corrections, ask payroll whether an amended wage statement is needed.
Retro pay calculator FAQs
How do I calculate retro pay after a raise?
Subtract the old hourly rate from the corrected hourly rate, multiply by affected regular hours, and add the applicable overtime correction. If the rates differ week by week, calculate each employer-defined workweek separately. Subtract only previously paid retro corrections tied to those weeks.
Can retroactive pay include overtime?
Yes. For covered nonexempt employees, a retroactive rate increase may also change overtime compensation owed in affected workweeks under 29 CFR § 778.303. Bonuses and multiple job rates can require more advanced calculations.
Is retro pay taxed at 22% in 2026?
Not automatically. Eligible separately identified supplemental wages may be subject to an optional 22% federal income-tax withholding method. Employers must follow the applicable IRS requirements. Social Security, Medicare, and applicable state or local withholding are separate.
What's the difference between retro pay and back pay?
Retro pay often describes correcting a previously paid rate or salary, while back pay can refer more broadly to unpaid wages. The terminology overlaps in practice. The important question is which earnings were due, what was already paid, and what remains unpaid.
What if I was paid retro pay on the next paycheck?
Check whether an added earnings line identifies the prior-period correction. Compare that amount with the gross workweek difference before deductions and with any earlier corrections. Do not edit or replace an employer-issued statement yourself.
What if the corrected rate changed more than once?
Use Workweek audit and enter the prior rate and correct rate separately for each affected workweek. If a single workweek contains multiple different rates, splitting the week into entries without accounting for weighted regular-rate rules may not be accurate; ask payroll for a specialized calculation.
Can a salaried worker receive retroactive overtime?
Yes, if the worker is legally nonexempt. Being paid a salary does not by itself exempt an employee from overtime. The salary calculator is a base-salary proration example, not a substitute for nonexempt regular-rate and overtime analysis.
Can I download my retro pay calculation?
Yes. After calculating, use Download CSV for the period-by-period figures, Copy audit for a text summary, or Print results for a printer-friendly view. These are calculation worksheets, not employer-issued payment records.
Need to document corrected, employer-approved earnings?
Once gross wages, withholding, and earnings categories have been verified, explore the ePaystubs pay stub generator for authorized payroll records. Confirm that the generator supports your specific retro adjustment format before creating a statement. The calculator above does not itself issue wages or a pay stub.
Explore the Pay Stub Generator →Never fabricate an employer's payroll history or misrepresent compensation as paid.
Methods, sources, and editorial transparency
The calculator uses the rate-difference method outlined above, with separate workweek rows, straight-time and overtime rate adjustments, and an optional modeled withholding worksheet. The calculator rounds each workweek's corrected and original gross to cents before taking the difference; payroll systems may use different rounding at the earnings-line level. The examples are original fictional illustrations created for this guide. All demonstrated cases use fictional earnings; this tool is not a payroll processor and no named payroll professional has independently certified it. All input and calculations run within the browser, and results are not sent to ePaystubs by this self-contained code. Employers should verify calculations in their own payroll systems.
- 29 CFR § 778.303 — retroactive increases affect the FLSA regular rate and overtime adjustments.
- 29 CFR Part 778 — more complex regular-rate computations.
- IRS Publication 15 (2026) — supplemental wage withholding and employee FICA rules.
- IRS Topic 751 — employee Social Security and Medicare withholding rates.
- SSA 2026 taxable maximum — $184,500 Social Security wage base.
- Department of Labor Fact Sheet 23 — federal overtime-pay basics.
Updated October 14, 2026. Reviewed against IRS Publication 15 (2026) and 29 CFR § 778.303 for the supported examples. Information is intended for general US payroll education and does not replace tax advice, legal advice, or an employer's payroll records. Standards and special cases may change.