How to Calculate Gross Monthly Income From Weekly or Biweekly Pay Stubs
Gross monthly income from pay stubs
Read the current gross pay on your stub, before taxes and deductions. If you earn that same amount each week, multiply it by 52 ÷ 12. If you earn it every two weeks, multiply it by 26 ÷ 12. This gives an annualized monthly average, which can differ from what your employer actually paid in one calendar month.
Weekly current gross × 52 ÷ 12; biweekly current gross × 26 ÷ 12. A biweekly $2,400 check gives a $5,200 average month, while two such checks paid in one month total $4,800 and three total $7,200. If pay changes, average comparable checks before converting. A landlord, lender or benefits program may prescribe its own method.
Which Number on the Pay Stub Is Gross Pay?
Find the Gross Pay, Gross Earnings or Total Earnings line in the Current or This Period column. It represents this payroll period's earnings before employee tax withholding and other deductions. A separate YTD column accumulates amounts across earlier checks. Net pay or your bank deposit answers a different question. Compare the labels with the CFPB's labeled pay stub or our guide to reading a pay stub.
| Figure | What it shows | Use in the basic conversion? |
|---|---|---|
| Current gross | Gross earnings on this check | Yes, if this is representative pay |
| Gross YTD | Accumulated gross from this employer this year | Use a separate historical calculation with the number of included checks |
| Net pay | Pay after withholding and deductions | No, if the question asks for gross |
| W-2 Box 1 | Federal taxable wages for a tax year | No, not automatically the same as total payroll gross |
A traditional 401(k) employee contribution, for example, is generally excluded from W-2 Box 1 wages even though it came from gross wages. The IRS explains that Box 1 treatment. If the stub has several earning lines, review whether bonuses, commissions, tips or non-wage reimbursements are included in its gross total; ask payroll about an unfamiliar line.
Choose the Monthly Income Figure You Actually Need
| Question | Method | Example for $2,400 biweekly |
|---|---|---|
| What is my typical annualized monthly gross? | Representative biweekly gross × 26 ÷ 12 | $5,200 average |
| What gross was actually paid in a specific month? | Add current gross on checks with pay dates in that month | $4,800 with two checks; $7,200 with three |
| What does my YTD history average? | Gross YTD ÷ comparable checks included × 26 ÷ 12 | Depends on the YTD and check count |
For steady weekly pay, use gross × 52 ÷ 12, about 4.3333 checks per average month. For steady biweekly pay, use gross × 26 ÷ 12, about 2.1667 checks. For semimonthly pay on two scheduled dates each month, use gross × 2. These fixed-base conversions appear in Fannie Mae's monthly-income table. Biweekly means every 14 days; semimonthly means twice per month.
A representative weekly stub showing $900 gross gives $900 × 52 ÷ 12 = $3,900 average gross per month. Four $900 checks paid in a calendar month total $3,600; five total $4,500. Neither amount replaces the $3,900 annualized average.
One Pay History, Four Valid Monthly Answers
Here is a fictional, mathematically reconciled example from one employer's biweekly payroll. The first five checks were $2,000 gross each. The sixth included $400 of extra earnings; the seventh returned to $2,000. Pay dates determine which month received each check. No personal or employer record is shown.
| Pay date | Current gross | Gross YTD | Why it matters |
|---|---|---|---|
| March 6 | $2,000 | $10,000 | Fifth check of the year |
| March 20 | $2,400 | $12,400 | Sixth check includes $400 extra |
| April 3 | $2,000 | $14,400 | Seventh check; extra pay did not repeat |
The $400 explains much of the difference. The recent sample is only about six weeks of biweekly checks, whereas the YTD average covers seven checks. If those extra earnings were a one-time bonus, the latest regular check may better reflect base pay; if they recur, a longer, representative history helps. The organization reviewing income decides which documents and method it accepts.
Gross Monthly Income Calculator From Pay Stubs
Use current gross amounts from genuine stubs. Enter dollars with or without commas, such as 2400 or 2,400.00. Calculations run in your browser; this tool does not submit entered amounts. Do not enter names or account numbers.
Recent checks from the same employer and pay schedule. Enter comparable consecutive checks. Dates are optional for the average, but required to calculate gross paid in a selected month. Leave an unusual check in the list only if you want it reflected in the recent average.
A selected month totals checks by their pay dates, not the dates when the work was done.
Gross YTD is an employer's running total, not a monthly figure. Use this mode only when you know how many comparable paychecks that total includes. If you changed jobs, got a raise or have unusual earnings, read the YTD limitations below.
Optional when entering several checks. Both fields must be filled to compare the historical average. It does not establish qualifying income.
Enter your gross pay and select Calculate.
This is a mathematical estimate. It does not verify wages, calculate taxes, or determine what a lender, landlord or agency will accept.
When Recent Checks and YTD Disagree
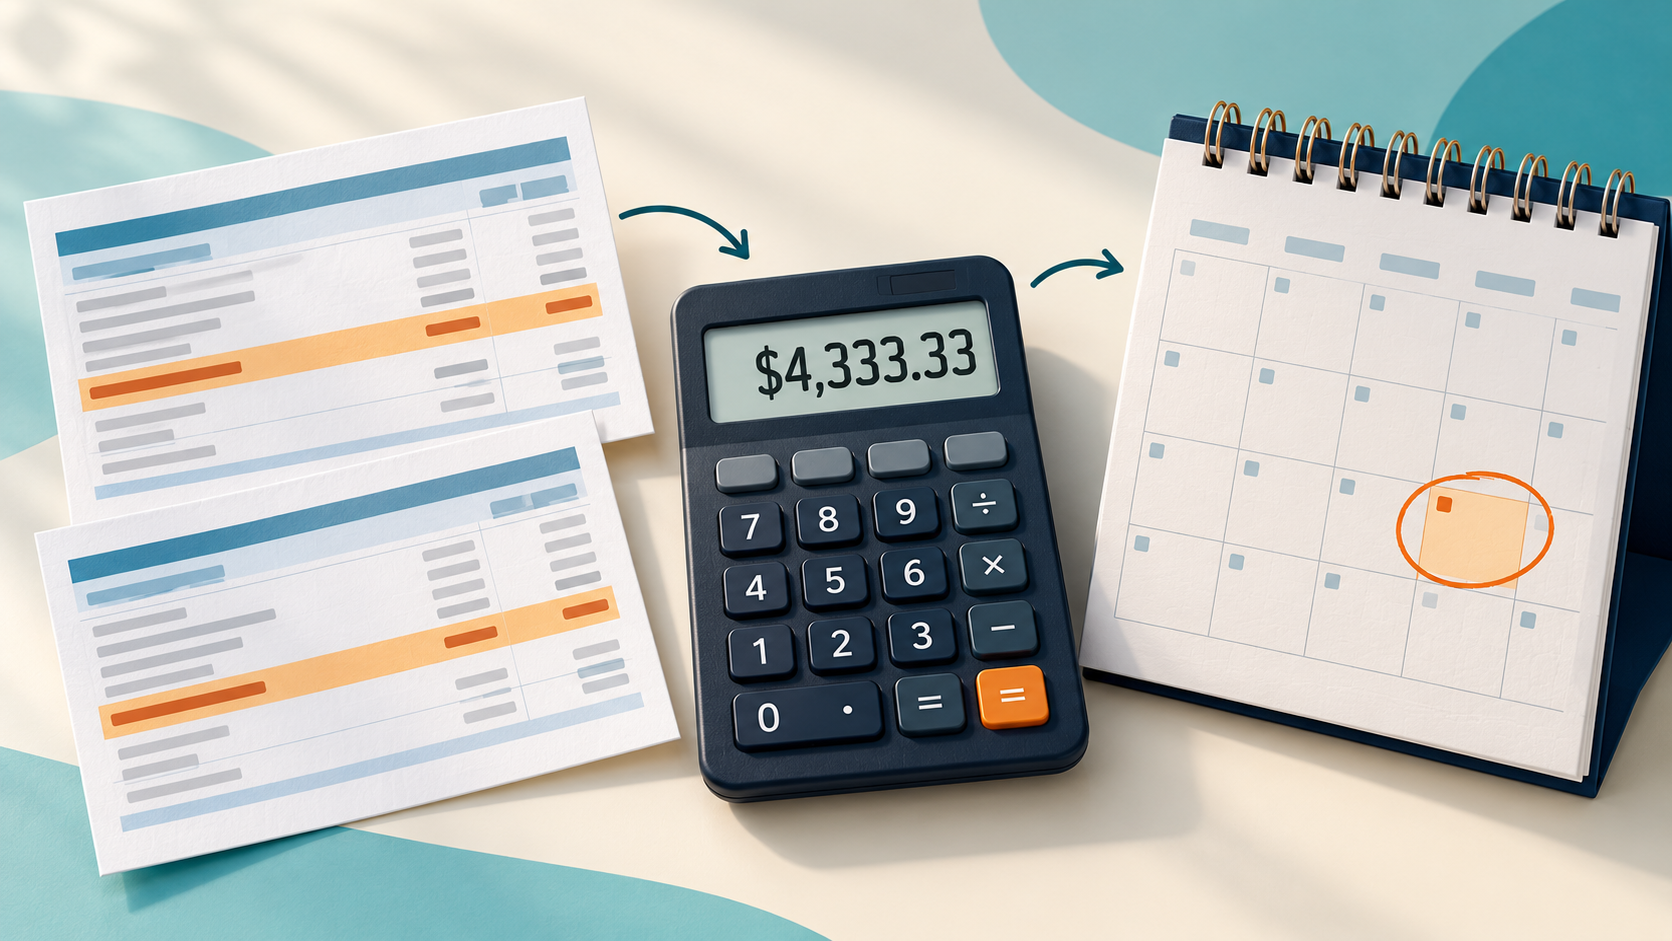
The YTD method takes the employer's gross YTD, divides by the number of comparable paychecks actually included, then converts that average check to a month. For example, $26,000 gross YTD across 13 comparable biweekly checks ÷ 13 × 26 ÷ 12 = $4,333.33 per month. Dividing a partial-year $26,000 YTD by 12 would give $2,166.67 and understate this historical average. A final full-year YTD may answer a different question: what the employer paid during the completed calendar year.
Check the first included paycheck and the employer before using YTD. A person hired in June does not have that employer's earnings for January through May. A raise can make old YTD checks less representative of current pay. A bonus can make one check less representative of regular pay. Payroll adjustments can also change a cumulative total. The IRS describes current-period gross and gross YTD on a pay stub; our current versus YTD guide explains the columns in detail.
A short run of changing checks estimates recent pay; YTD measures the included history. Neither automatically predicts a future year. Fannie Mae distinguishes fixed base income from fluctuating hours or pay and applies separate history and documentation rules to variable base income, overtime and bonuses. Do not treat a four-check personal average as a mortgage approval figure. Read Fannie Mae's base-income guidance.
Why Another Application May Show a Different Monthly Number
A standard fixed-pay annualization is not a universal program rule. Fannie Mae uses weekly × 52 ÷ 12 and biweekly × 26 ÷ 12 for fixed base pay. As a different, program-specific example, the Illinois Department of Human Services uses 4.3 and 2.15 after specified rounding steps. Follow the method required by the particular recipient; do not substitute this calculator for its instructions.
Also identify the date being counted. Gross paid in March means add checks whose pay dates fall in March; the work periods can cross month boundaries. At year end, this distinction matters for wage reporting: the IRS gives an example of December work paid on January 1 that belongs on the following year's W-2. See the IRS W-2 instructions. For your employer's actual schedule and any extra biweekly payday, use our pay-period and payday guide.
A standard biweekly conversion uses 26 pay periods, but some calendar years and employer cycles contain 27 pay dates. The number of paydays in a calendar year and the way an employer divides a fixed salary are related questions that can produce different per-check amounts. ADP notes the 27-period possibility; confirm the employer's calendar instead of changing the calculator's standard annualization automatically.
Common Questions
Is gross monthly income printed on a weekly or biweekly pay stub?
Usually the stub shows current gross for one pay period and may show gross YTD. Use the pay schedule to estimate an average month. If the question is about one named calendar month, total the current gross on checks paid during that month.
Should I multiply a weekly check by four or a biweekly check by two?
Those shortcuts describe four weekly or two biweekly checks, which some individual months contain. They understate the standard annualized monthly average: use weekly × 52 ÷ 12 or biweekly × 26 ÷ 12.
Should overtime, tips or a bonus be included?
Such earnings can be part of a current gross amount, but one unusual check can distort a projection. Compare comparable checks and identify regular versus exceptional earnings. The organization reviewing an application decides its treatment of variable pay.
Can I divide W-2 Box 1 by 12 instead?
Box 1 reports federal taxable wages and can differ from total gross payroll earnings because of certain pretax deductions. It can describe a completed tax year, but it is not a direct substitute for the current gross lines on pay stubs. See our W-2 versus pay-stub wage guide.
What if I have two jobs?
Calculate each employer's pay separately using its own frequency and representative checks, then add the compatible monthly estimates. Do not divide one employer's YTD by a combined count of checks from both employers.
An employer or authorized preparer can use ePaystubs to format accurate earnings, deductions and pay dates. Employees seeking an original historical stub should request it from their employer or payroll portal; a newly generated document is not a replacement for an employer-issued record.
Sources and calculation scope
- IRS: current gross and YTD on a pay stub
- CFPB: labeled pay stub
- Fannie Mae: fixed and variable base income
- Illinois DHS: program-specific income conversion
- IRS: W-2 wages paid in a calendar year
All worked figures above are fictional and arithmetically checked. This U.S. guide provides educational calculations, not individualized tax, legal, lending or benefits advice. Check the rules of the organization reviewing your income and use genuine payroll records.