W-2 Boxes Explained: Complete Guide to Every Box & Box 12 Code (2026)
ePaystubs Editorial Team · Tax year 2026 · Updated September 22, 2026 · Source-checked against IRS instructions
Form W-2 reports annual employee wages, withholding and certain benefits. Box 1 is federal taxable wages, Box 2 is federal income tax withheld, and Boxes 3–6 cover Social Security and Medicare wages and taxes. Box 12 reports special items by capital-letter code. If your form says 12c W 1,500, “12c” means the third reporting position, “W” is the IRS code for reportable HSA contributions, and $1,500 is the reported amount. Do not confuse the lowercase position with Code C or treat every Box 12 amount as extra taxable income.
Check the year: this guide covers wages paid in tax year 2026, normally reported on a W-2 provided in early 2027. A W-2 received in early 2026 generally reports tax year 2025.
W-2 Box 12 Codes: Search the Complete Reference
Enter the capital-letter code or copy the entire Box 12 entry, such as 12c W 1500, 12b Code D 3200 or DD. The finder separates the lowercase position from the uppercase IRS code and explains the entry without asking for your name, SSN or employer details. All 33 code definitions remain readable below even if JavaScript is unavailable.
Enter only the code and optional amount. Do not enter an SSN, employee ID or identifying details. This tool runs locally in your browser.
Showing all 33 code entries.
| Code | IRS meaning | How to interpret it |
|---|---|---|
| A | Uncollected Social Security or RRTA tax on tips | May require additional tax reporting; confirm your return instructions. |
| B | Uncollected Medicare tax on tips | Not the same as regular Medicare withholding in Box 6. |
| C | Taxable cost of group-term life insurance over $50,000 | Generally already included in applicable wage boxes; do not add it again. |
| D | Employee elective deferrals to a 401(k), including SIMPLE 401(k) | Traditional pre-tax deferrals generally reduce Box 1, not Social Security or Medicare wages. |
| E | Employee elective deferrals under a 403(b) salary reduction agreement | Traditional pre-tax deferrals generally reduce Box 1, not Social Security or Medicare wages. |
| F | Employee elective deferrals under a section 408(k)(6) SARSEP | Check the plan type and the employer’s retirement records. |
| G | Deferrals under a section 457(b) plan | Income-tax treatment varies by plan and deferral type; not always comparable to a 401(k). |
| H | Elective deferrals to a section 501(c)(18)(D) plan | Do not assume this is the same federal tax treatment as a traditional 401(k). |
| J | Nontaxable sick pay | This portion is not included in taxable wages. |
| K | 20% excise tax on excess golden parachute payments | A tax amount, not a retirement contribution. |
| L | Substantiated employee business expense reimbursements | Generally reimbursement reporting rather than new taxable pay. |
| M | Uncollected Social Security or RRTA tax on taxable group-term life insurance for former employees | Distinct from Code C, which reports taxable insurance cost. |
| N | Uncollected Medicare tax on taxable group-term life insurance for former employees | Distinct from Code C, which reports taxable insurance cost. |
| P | Excludable moving expense reimbursements for eligible Armed Forces or intelligence community members | Special eligibility rules apply. |
| Q | Nontaxable combat pay | May be relevant to certain tax credit elections; check filing instructions. |
| R | Employer contributions to an Archer MSA | Not an HSA contribution; compare with your applicable account records. |
| S | Employee elective deferrals under a section 408(p) SIMPLE IRA plan | Do not confuse with Code D for a SIMPLE 401(k). |
| T | Employer-provided adoption benefits | Tax exclusion depends on eligibility and applicable limits. |
| V | Income from exercising nonstatutory stock options | Usually included in wage boxes; do not add it to Box 1 again. |
| W | Employer HSA contributions, including employee salary reductions through a cafeteria plan | Report appropriately on Form 8889; do not treat payroll Code W as a second personal contribution. |
| Y | Deferrals under a section 409A nonqualified deferred compensation plan | This code is not required for all 409A deferrals; check the plan and IRS instructions. |
| Z | Income under a 409A plan that fails applicable requirements | May already be in Box 1 and can trigger additional tax; seek qualified advice. |
| AA | Designated Roth contributions under a 401(k) plan | After-tax contribution: does not lower Box 1 wages. |
| BB | Designated Roth contributions under a 403(b) plan | After-tax contribution: does not lower Box 1 wages. |
| DD | Cost of employer-sponsored health coverage | Generally informational; the reported coverage cost is not itself extra taxable income. |
| EE | Designated Roth contributions under a governmental 457(b) plan | After-tax contribution: does not lower Box 1 wages. |
| FF | Permitted benefits under a qualified small employer HRA (QSEHRA) | Reports permitted benefit, not automatically an employee-paid deduction. |
| GG | Income from qualified equity grants under section 83(i) | Taxable amount is generally already reflected in applicable wage reporting. |
| HH | Aggregate deferrals under section 83(i) elections | Do not assume the entire balance is newly taxable in the current year. |
| II | Medicaid waiver payments excluded from gross income under applicable IRS rules | Not a general-purpose Medicaid benefit code. |
| TA | Employer contributions under a section 128 Trump account contribution program | New 2026 code; applies to eligible employer contributions under the program. |
| TP | Total cash tips reported to the employer | New 2026 code; not every reported tip automatically meets deduction eligibility. |
| TT | Total qualified overtime compensation | New 2026 code; generally the required FLSA premium above regular pay, not all overtime wages. |
Coverage: These are the Box 12 codes listed in the IRS 2026 W-2 instructions. The IRS may use separate reporting rules for territorial, railroad or other special forms; always match the code to the form and tax year you actually received.
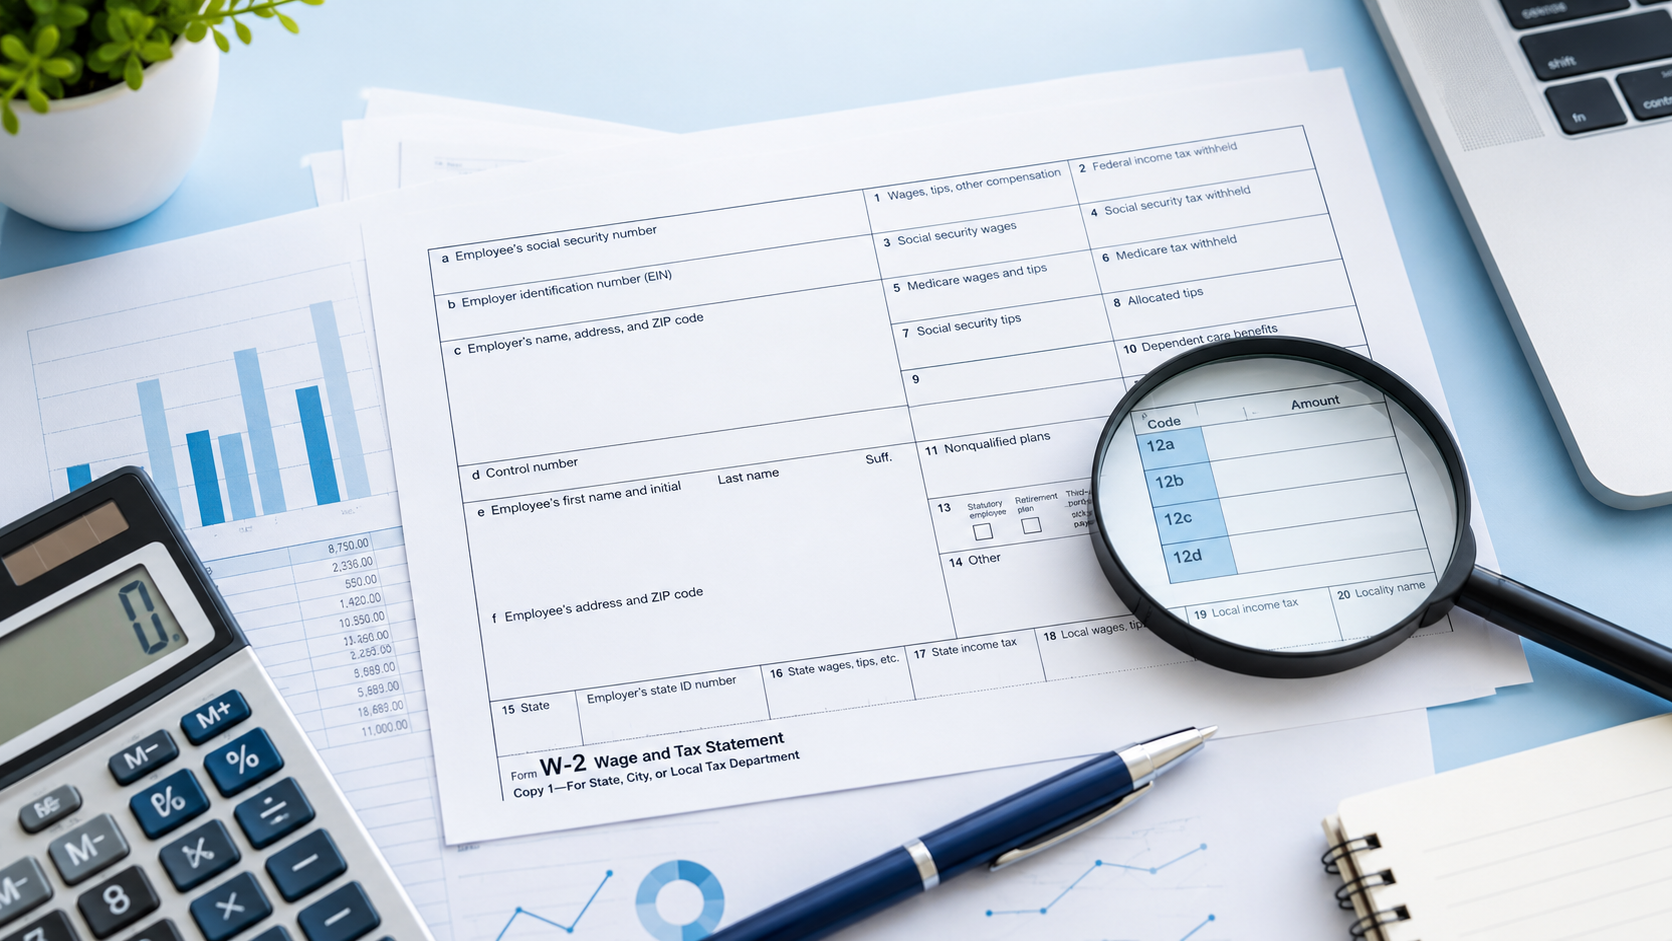
What Do 12a, 12b, 12c and 12d Mean on a W-2?
The first slot holds Code D: a $3,200 traditional 401(k) elective deferral, generally already excluded from federal Box 1 wages.
The second slot holds Code DD: $7,500 of reported employer-sponsored health coverage cost. The reported amount itself does not create additional taxable wages.
The third slot holds Code W: $1,500 of HSA contributions reported through employer/payroll arrangements. Coordinate this amount with Form 8889 rather than claiming it again as a separate personal HSA contribution.
The fourth slot holds Code AA: $2,000 in designated Roth 401(k) contributions. This is an after-tax employee contribution and does not reduce Box 1 wages.
The lowercase a–d after “12” mark four positions on the standard printed W-2. They are not tax codes. The uppercase code in each position determines the reported item. A line marked “12b D 3200.00” reports a Code D retirement deferral; the letter b does not change its tax treatment.
The IRS Copy A has four standard Box 12 entry slots. An employer reporting more than four items on Copy A uses additional forms following the IRS multiple-form rules without duplicating federal wage and withholding totals. Approved substitute employee copies may show more than four Box 12 entries. Ask payroll before assuming two statements from the same employer represent duplicate wages. IRS: Multiple forms and Box 12 codes.
What Does Every W-2 Box Mean?
Start with your identifying information, then compare annual wage figures with the final pay stub. Not every employer uses every box.
| Box | What it reports | What to check |
|---|---|---|
| a | Employee Social Security number | Confirm it belongs to you; some employee copies may truncate it. |
| b | Employer identification number (EIN) | Check the issuer if you worked for more than one employer. |
| c | Employer name and address | Use the correct employer record for your tax return. |
| d | Employer control number, if used | An internal identifier; may be blank. |
| e / f | Employee name and address | Check spelling and personal information. |
| 1 | Federal taxable wages, tips and other compensation | May differ from gross earnings due to qualifying pre-tax benefits and taxable additions. |
| 2 | Federal income tax withheld | Compare with your year-end federal withholding total. |
| 3 | Social Security wages | For 2026, regular covered wages are subject to the $184,500 wage base per employer. |
| 4 | Employee Social Security tax withheld | Typically 6.2% of Box 3, up to $11,439 in 2026 for one employer (special cases differ). |
| 5 | Medicare wages and tips | No annual Medicare wage cap; can exceed Box 3. |
| 6 | Medicare tax withheld | Usually 1.45%, plus employer withholding of 0.9% Additional Medicare Tax after $200,000 of wages from that employer. |
| 7 | Social Security tips reported to the employer | See whether your reported tips were included correctly in wage reporting. |
| 8 | Allocated tips | Generally not included by the employer in Boxes 1, 3, 5 or 7; tax reporting may require further action. |
| 9 | Unused / generally blank | Do not enter a wage or tax amount here. |
| 10 | Dependent care benefits provided through the employer | For 2026, the general exclusion limit increased to $7,500 ($3,750 if married filing separately), subject to applicable eligibility and expense limits. The box reports the total benefit. |
| 11 | Certain nonqualified deferred compensation amounts | Follow the specific instructions; not a general retirement-plan balance. |
| 12 | Letter-coded compensation and benefit items | Use the capital-letter code lookup above; do not add all amounts to Box 1. |
| 13 | Statutory employee, retirement-plan participant and third-party sick-pay checkboxes | Retirement-plan status can affect eligibility for some IRA deductions. |
| 14a | Other information such as union dues or state insurance deductions | Employer-defined descriptions need their own documentation; not all are deductible. |
| 14b | Treasury Tipped Occupation Code(s), when Code TP cash tips are reported | New 2026 reporting field; check the occupation code with the employer if needed. |
| 15 | State and employer’s state identification number | Confirm applicable work and tax jurisdictions. |
| 16 / 17 | State wages and state income tax withheld | State wage treatment can differ from federal Box 1. |
| 18 / 19 / 20 | Local wages, local income tax and locality name | Relevant only where local reporting applies. |
What Changed on the 2026 W-2? TA, TP, TT and Box 14b
The IRS introduced three Box 12 codes for the 2026 tax year and split the former Box 14 into Box 14a (“Other”) and Box 14b (Treasury tipped occupation codes). A W-2 for tax year 2025 is a different form; do not look for mandatory 2026 code reporting on the prior-year form.
Reports eligible employer contributions under a section 128 Trump account contribution program for an employee or dependent. A reported amount is not necessarily wages that the employee received in cash.
Reports the total cash tips reported, not a guaranteed qualified-tips deduction. Occupation, income, filing and other statutory conditions still apply. Employers use Box 14b for the associated Treasury Tipped Occupation Code(s).
Reports overtime compensation meeting the relevant federal definition, generally the premium above regular pay required by FLSA section 7. It does not mean all overtime wages or all state-law overtime is deductible.
When employers report cash tips with Code TP, the IRS instructions require one or more occupation codes in this new field. Code 14b is not an additional dollar amount or separate tax.
An employee’s regular hourly rate is $20 and the required time-and-a-half overtime rate is $30. For five eligible overtime hours, overtime wages total $150, but the premium portion is $50 ($10 × five hours). In this simplified example, the $50 premium, not the full $150, is the relevant Code TT amount. Other statutory requirements can change an actual deduction.
Tips and overtime remain subject to applicable payroll withholding rules. A Code TP or TT figure is an employer reporting amount, not automatic approval of a personal income-tax deduction. See the IRS 2026 reporting instructions for the detailed definitions.
Which Box 12 Codes Affect Taxable Wages?
Instead of labeling the entire Box 12 column “taxable” or “nontaxable,” identify the specific entry:
| Example code | Current meaning | How it relates to taxes |
|---|---|---|
| D / E | Traditional employee 401(k) / 403(b) deferrals | Generally excluded from federal Box 1 but included in Social Security and Medicare wage bases. |
| AA / BB / EE | Designated Roth retirement deferrals | After-tax contributions are already counted in federal wages; do not subtract them from Box 1 again. |
| DD | Cost of qualifying employer health coverage | Informational reporting; the Code DD total is not itself additional taxable wages. |
| W | HSA contributions through employer / eligible payroll plan | Generally excluded when eligible; use the proper employer-contribution section of Form 8889, not an extra personal-contribution deduction. |
| C / V / Z | Specified taxable benefit or compensation items | Can already be in applicable wage boxes; Code Z can trigger additional tax. Do not blindly add the same reported amount twice. |
| TP / TT | Cash tips reported / qualified overtime compensation | Reporting may support a return-level deduction if the individual satisfies its separate requirements; it does not remove ordinary payroll taxes. |
Code D vs. Code DD
D reports employee deferrals to a 401(k); qualifying traditional deferrals generally lower federal Box 1 wages. DD reports the cost of employer-sponsored health coverage for information only. A $12,000 Code DD entry does not mean the employee owes $12,000 or received $12,000 of extra taxable pay.
Code W and Form 8889
Code W includes eligible employer HSA contributions and employee contributions through a qualifying cafeteria plan. Those payroll amounts belong in the employer-contribution treatment on Form 8889, not as an additional out-of-pocket contribution you can deduct again. Separate eligible contributions paid directly from your after-tax funds can have different reporting. See IRS Form 8889 instructions.
Worked Example: Why Box 1 Can Differ From Box 3 and Box 5
The following fictional employee earned $60,000 during 2026, contributed $3,000 to a traditional 401(k), and paid $2,400 in qualifying pre-tax health premiums through payroll. Assume no additional taxable benefits, wage-base limitation or other special payroll adjustments.
| Item | Calculation | Example amount |
|---|---|---|
| Gross wages | Annual earnings before listed deductions | $60,000.00 |
| Box 1 federal wages | $60,000 − $3,000 401(k) − $2,400 health premium | $54,600.00 |
| Box 3 Social Security wages | $60,000 − $2,400 health premium | $57,600.00 |
| Box 4 Social Security tax | $57,600 × 6.2% | $3,571.20 |
| Box 5 Medicare wages | $60,000 − $2,400 health premium | $57,600.00 |
| Box 6 Medicare tax | $57,600 × 1.45% | $835.20 |
| Box 12 Code D | Employee traditional 401(k) deferral | $3,000.00 |
What this demonstrates: The 401(k) deferral reduces Box 1 but not the standard Social Security or Medicare wage bases; the qualifying health premium reduces all three in this simplified example. Box 2 depends on the employee’s actual federal withholding and cannot be inferred from gross wages alone. Box 12 Code DD, if shown, reports qualifying total employer-sponsored coverage cost rather than automatically equaling the employee’s $2,400 premium.
For the full method, read how to calculate W-2 wages from a pay stub, the FICA guide, and how to read your final pay stub.
How to Check Your W-2 Against Your Final Pay Stub
- Confirm the tax year and employer. A 2026 W-2 reports wages paid during 2026; a late paycheck can belong to the following year.
- Compare annual wage totals. Work from the final year-to-date gross and taxable-wage fields, accounting for the actual treatment of benefits and taxable additions.
- Reconcile Boxes 2, 4 and 6. Use year-to-date withholding for federal income tax, Social Security and Medicare, allowing for corrections or multiple employers.
- Match each Box 12 code separately. Compare traditional retirement, Roth deferrals and HSA totals to the appropriate payroll records. Do not combine different code types.
- Review Boxes 10, 13 and 14. Confirm dependent care, retirement-plan status, additional employer details and any 2026 tipped-occupation code.
Quick reconciliation worksheet: which number should match?
| W-2 item | Compare with your records | Do not assume |
|---|---|---|
| Box 1 | Final YTD federal taxable wages after qualifying exclusions and taxable additions | That it must equal gross pay or a simple gross-minus-all-deductions figure. |
| Box 2 | Federal income tax actually withheld during the tax year | That it equals a tax-bracket percentage of Box 1. |
| Boxes 3 / 4 | Social Security taxable wages and tax withheld | That Box 3 always equals Box 5; 2026 wages are subject to a $184,500 wage base for each employer. |
| Boxes 5 / 6 | Medicare taxable wages and Medicare tax, including any Additional Medicare withholding | That Medicare stops at the Social Security wage ceiling. |
| Box 12 D / AA | Separate traditional and Roth retirement-plan YTD contributions | That Roth AA should be subtracted from Box 1 like traditional D. |
| Box 12 W | Employer HSA amounts plus qualifying employee cafeteria-plan salary reductions | That this entire amount is an extra deduction to enter again as a personal contribution. |
| Box 12 DD | Employer-sponsored health coverage cost reported for information | That it is an employee deduction or newly taxable income. |
What to ask payroll when the figures differ
“My [tax year] W-2 shows Box [number/code] of $[amount]. My year-end payroll record shows [field] of $[amount]. Please confirm the taxable-wage adjustment, pay date, or benefit treatment that explains the difference and whether a corrected W-2 is necessary.” Preserve your original forms; do not alter an issued W-2 or invent missing entries.
What If a W-2 Box or Box 12 Code Is Missing or Incorrect?
First check your employer’s payroll or benefits statement, not just the previous year’s W-2: different tax years and benefits can change which codes appear. If a 2026 W-2 entry is genuinely incorrect, contact the issuer, explain the discrepancy, and ask whether a Form W-2c is needed.
If you cannot obtain a correct W-2, the IRS provides procedures for missing or incorrect employer forms, including when Form 4852 is appropriate. Do not invent replacement figures or present a self-created pay statement as an official W-2. Start with IRS Form W-2 guidance and, if you need another copy, see our lost-W-2 guide.
W-2 Boxes and Box 12: Frequently Asked Questions
What does “12c W” mean on a W-2?
“12c” is the third Box 12 reporting slot; “W” identifies reportable HSA contributions, including qualifying employer and payroll salary-reduction contributions. The lowercase c does not change the meaning of Code W.
Is Box 12 the amount of tax I owe?
No. Box 12 holds different codes for benefits, taxes and compensation. Some report already-taxed income, some report qualifying pre-tax contributions, and others are informational. Use the capital-letter code rather than treating the entire total as a tax bill.
Do codes AA, BB or EE reduce Box 1?
No. These identify designated Roth retirement contributions. The corresponding employee amounts are generally after-tax and already included in federal wages, unlike eligible traditional elective deferrals.
Why does Box 3 differ from Box 1?
Traditional 401(k) deferrals generally reduce federal taxable wages but remain subject to Social Security tax; qualifying cafeteria-plan health premiums may reduce both. Box 3 also has the annual Social Security wage limit.
Can I claim the full Code TP amount as a tips deduction?
Not automatically. TP reports total cash tips to the employer. Deduction eligibility also depends on the individual’s occupation, the nature of the tips, income and other federal requirements. Box 14b reports the associated occupation code(s).
Do I need a 2026 Code TT on the W-2 I received in early 2026?
Usually not: a W-2 received in early 2026 generally covers tax year 2025, when the IRS provided reporting transition relief. Code TT applies to the 2026 tax-year reporting framework.
What is the difference between Code D and Code DD in Box 12?
Code D reports eligible 401(k) employee elective deferrals; traditional pre-tax deferrals generally reduce Box 1. Code DD is the reported cost of employer-sponsored health coverage and is informational. Neither the amount under DD nor the label “12d” is itself a 401(k) deduction.
Does Code W mean I can deduct the entire amount again?
No. Code W includes employer HSA contributions and employee HSA salary reductions through a qualifying cafeteria plan. These are generally recorded in the employer-contribution section of Form 8889; separate personal contributions outside payroll are handled differently. Review your actual HSA records and current Form 8889 instructions.
What if Box 12 reports more than four codes?
The standard IRS Copy A has four slots. Employers can use additional Copy A forms to report more items without duplicating federal wage/tax totals, and approved substitute employee copies may include more than four entries. Compare each code and ask payroll about genuine duplicates.
Official sources and related guidance
IRS instructions control the formal meaning of each code. If a source or your payroll portal appears inconsistent, check which tax year it describes.
Working with real W-2 figures?
Employers and authorized payroll users can organize accurate wage and withholding details using ePaystubs. A generated worksheet or draft is not a substitute for the W-2 the employer must issue and file.
Explore the W-2 form toolThis article provides general educational information for tax year 2026. Reporting rules and personal eligibility can differ; consult the current IRS instructions or a qualified tax professional for individual tax decisions. No personal tax return or employment record is verified by this article.